
The Offshore O&M decisions that define the next 20 years
by RES | Sep 18, 2026 | Reading time: 4 min
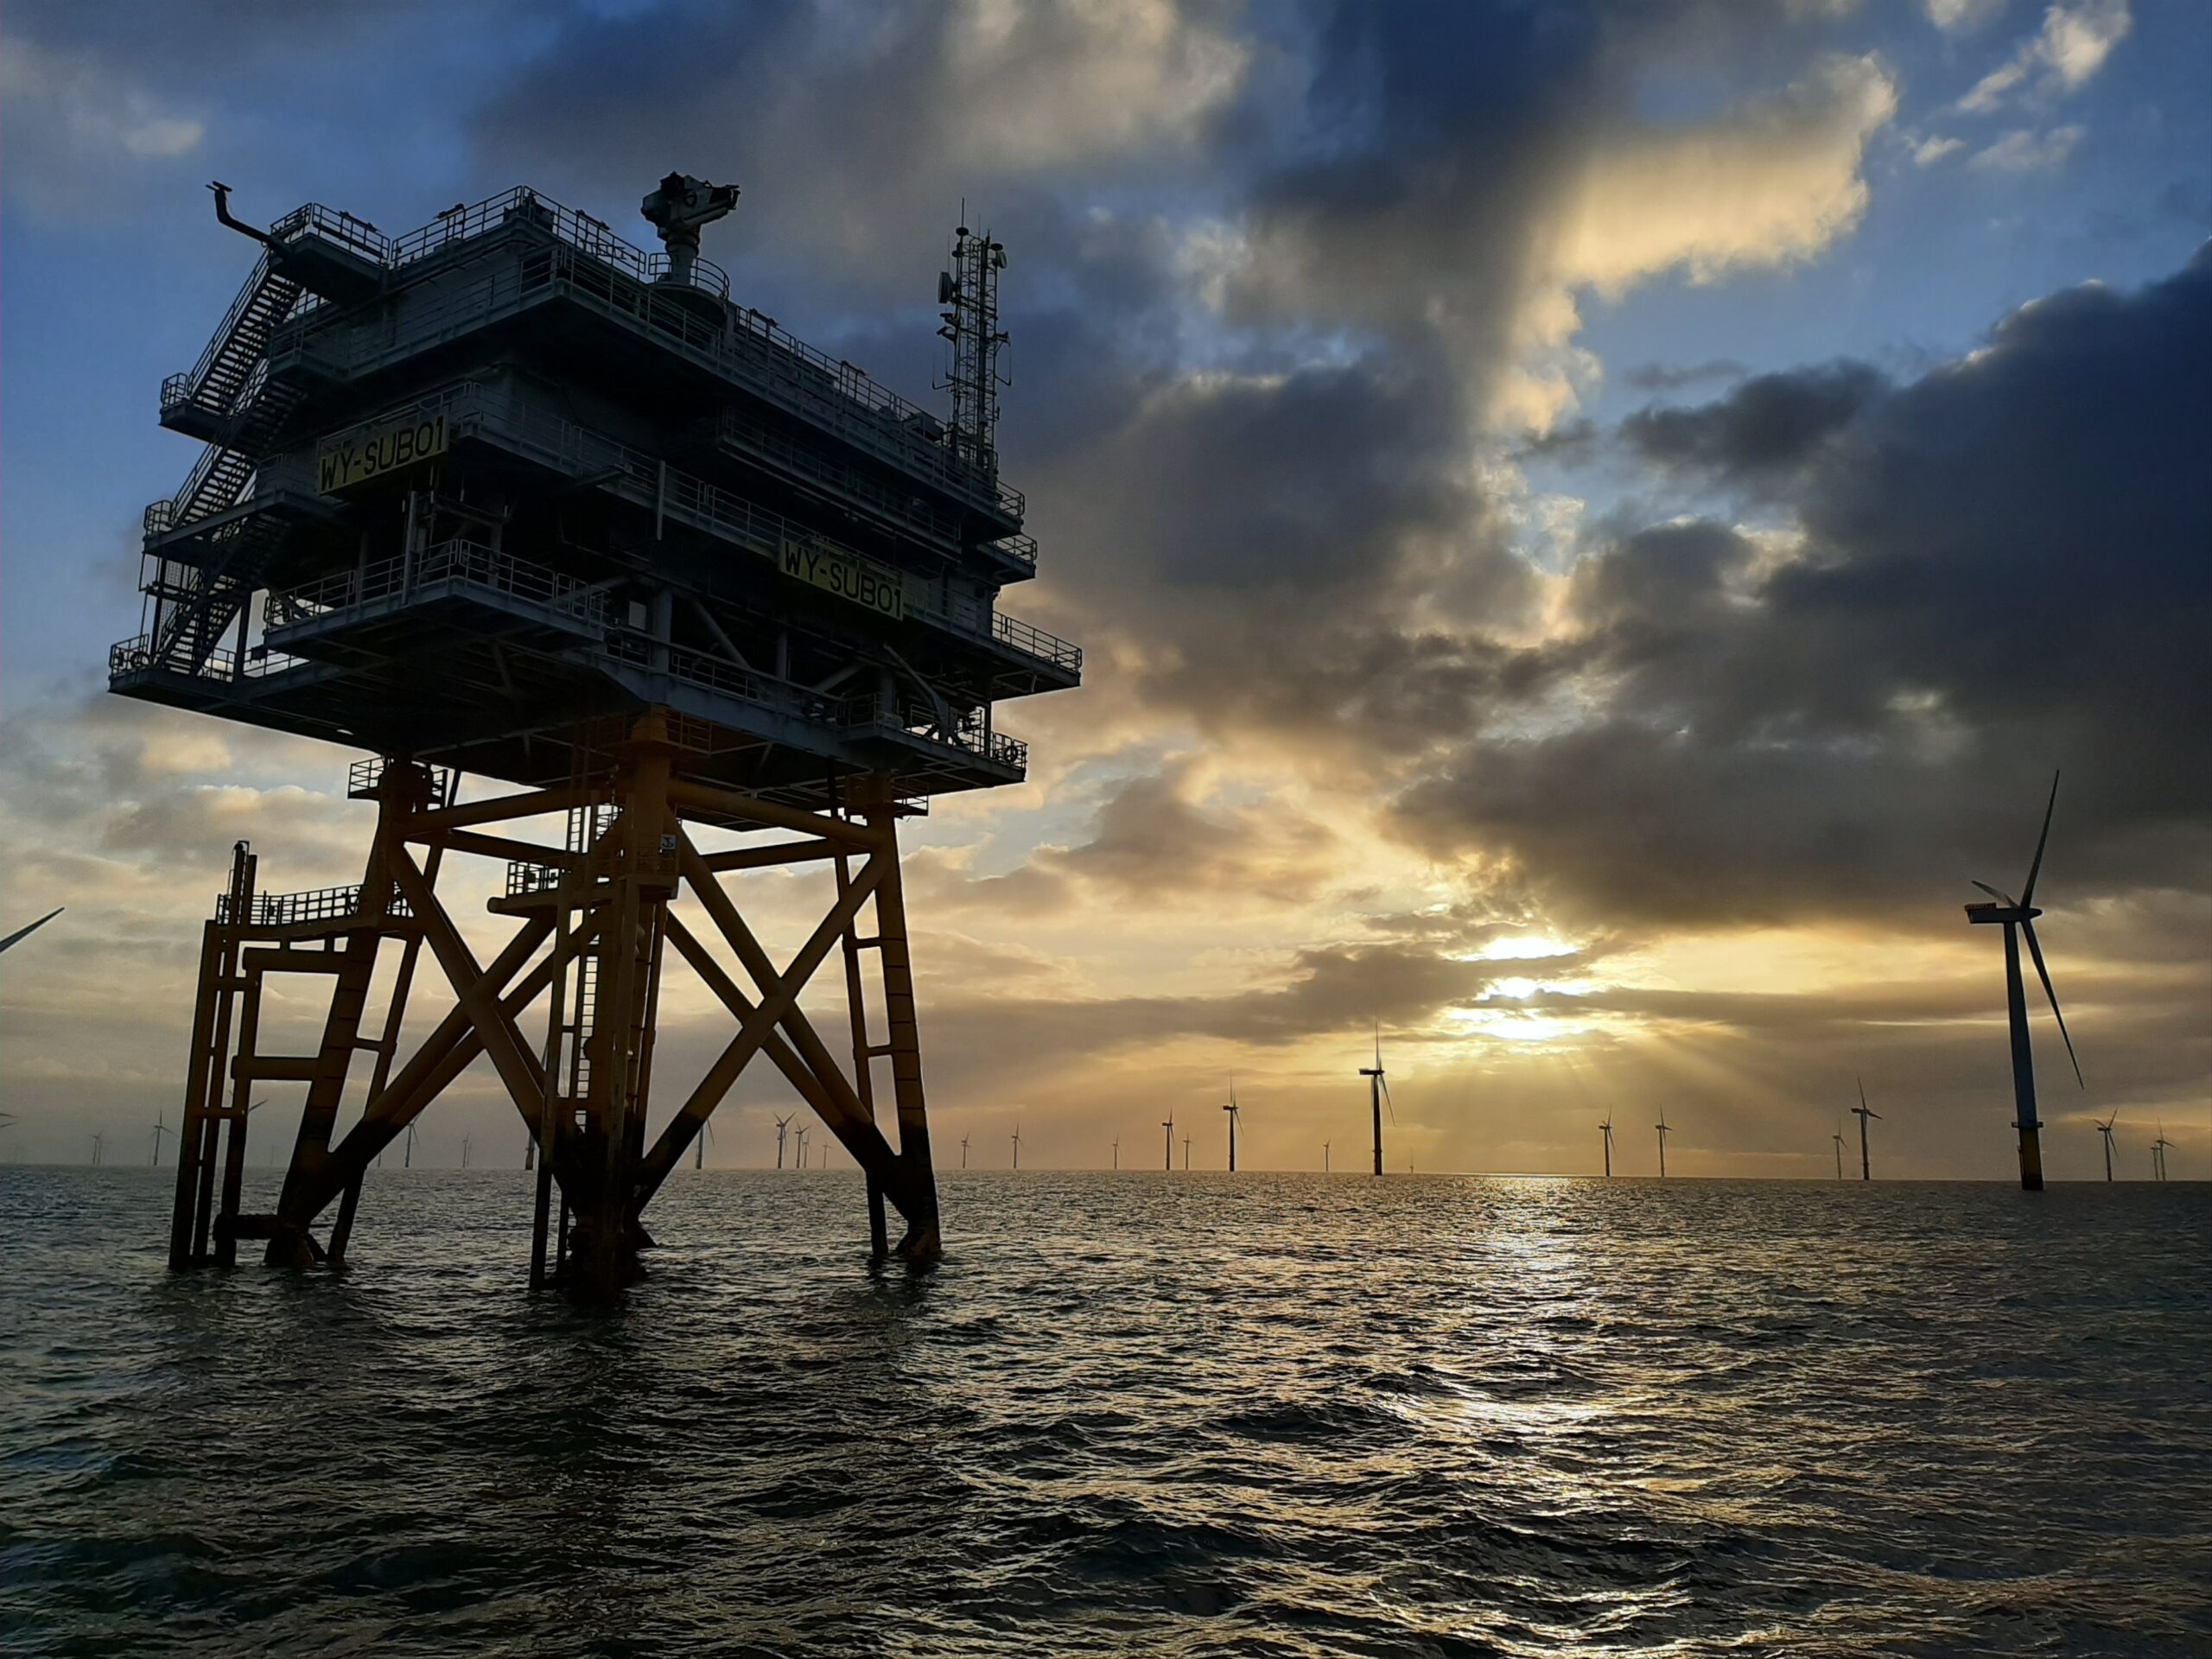
Offshore wind’s first generation of assets is growing up. Turbines are getting bigger, assets are ageing, and the operational decisions involved in keeping a maturing fleet performing well are multiplying. Research from digital planning and simulation solutions provider, Shoreline, found that almost a third of Europe’s installed wind capacity will approach 20 years of operation by 2030 – pushing owners toward a genuine three-way choice between repowering, extending asset life, or decommissioning. Whatever the final decision, the years leading up to it are what determine whether it’s a good one.
That’s the conversation worth having right now. Not just who can keep the turbines spinning, but who can do it well enough, for long enough, to give owners real, valuable options when the time comes to decide. RES has been answering that question across the offshore sector for over 15 years, delivering O&M services to Offshore Transmission Owner’s (OFTO) across six offshore transmission assets in the UK and one offshore substation in France, and balance of plant inspection and maintenance in UK and France.
Offshore Wind Spares & Repairs: Where the real risk sits
As offshore wind farms exit OEM warranty periods, component availability becomes one of the biggest threats to performance. Industry reporting has flagged equipment obsolescence and spares management as an escalating concern for ageing offshore assets, with operators turning to on-demand manufacturing and remanufactured parts as long lead times and discontinued components become routine.
It’s a problem that rewards preparation over reaction. Multi-supplier relationships, strong OEM partnerships, and genuine global operational reach mean critical components can be found when and where they’re needed – turning spares from an overhead into a source of resilience. Spare part warehouses and refurbishment workshops in Spain and the UK, position RES geographically and operationally with solutions that extend component life, minimise downtime and offer a cheaper, greener alternative to replacement.
That capability is proven at scale onshore. Today, RES provides asset management, operations and maintenance (O&M), and spare parts services to 31 GW of operational onshore wind assets worldwide, with technician training delivered through GWO-registered centres across Europe and Latin America. This in-house delivery model, spares network and engineering discipline, is now extended into offshore turbine maintenance and MCR contracts.
It’s RES’ own O&M teams, not a third party, who carry out the turbine maintenance and MCR work the parts are needed for. For any asset weighing up a life-extension decision, that end-to-end line from part to install sits close to the centre of the business case.
Offshore Wind HV Maintenance: Why the skills gap matters
Offshore wind is as much an electrical engineering challenge as a mechanical one – spanning FEED-stage grid studies and cable design, through construction support and commissioning, to fully wrapped operational services including 24/7 remote monitoring, SCADA fault resets, High Voltage (HV) Safety Rules compliance and grid liaison.
It matters more than it used to. The sector’s skills shortage is particularly acute in specialist electrical and HV roles, according to ORE Catapult — which makes genuine end-to-end HV depth one of the harder capabilities to source, and one of the easier ones to under-deliver on. For RES, it’s an extension of HV work already proven on live offshore transmission assets rather than a discipline being built from scratch.
Digital O&M: Data as the deciding factor
Owners increasingly want proof of capability, not just visibility. Bladena – a RES company – is currently running a full-scale torsional load test campaign with ORE Catapult on an 88-metre offshore blade, validating how large blades behave under real-world stress conditions and testing whether structural reinforcement solutions can reduce the deformation that leads to blade failure.
It’s the same principle behind RES’ wider digital portfolio: predictive analytics and condition-based monitoring that forecast spares needs, flagging issues earlier giving asset managers the transparency to plan rather than react – are what shift O&M from a reactive service into a genuine performance lever.
Repowering vs Life Extension: An honest note
Not every voice treats life extension as the default answer. Some argue repowering delivers more value per unit of capital on the strongest sites – the Shoreline research above makes clear this is a live debate. The scale involved backs that up, just not in offshore’s own data yet. WindEurope’s 2026-2030 outlook has European onshore wind already decommissioning and repowering at real volume, around 16GW reaching end of life between 2026 and 2030, with only half of that being repowered rather than removed. Offshore fleets haven’t hit that wall yet simply because they’re younger, but the same choice is coming, and the O&M decisions made now are what will shape which way it goes. That tension sharpens the case for strong O&M rather than undercutting it. Whichever path an owner takes, the interim years still need to be run safely and with reliable performance data – data that often determines which path is right in the first place.
The OWOP Alliance: A collective answer to a structural problem
None of this plays out in isolation. Through the Offshore Wind O&M Partnership (OWOP) – an alliance between RES, GEV Wind Power, Rix Renewables and Outreach Offshore – the full scope of core offshore O&M, including turbine maintenance and Major Component Replacement (MCR), is offered under a single contract, each partner bringing what they do best with the aim of more efficient, safer and cost-effective services.
The model matters more given the sector’s structural workforce gap: spreading resourcing risk across four established partners, rather than leaving it with one, is a meaningfully different proposition from a single-provider contract. It’s a model that travels too – in markets like Germany, where utilities and IPPs are weighing up who has the scale, breadth and depth to grow alongside them.
For a closer look at how the OWOP alliance is reshaping offshore O&M delivery in practice, including first-hand insight from Offshore Sales Manager, Felicity Hester, on why the industry has been “waiting for someone to do this” — read the full feature in Insight Energy, Issue 25, Autumn 2026: “O&M: Playing the Long Game.” (page 18)
Where this leaves owners
Owners entering the current North Sea tender cycle are making decisions that will shape their O&M relationships for the next 20 years. Wood Mackenzie notes that the UK’s AR7 auction, with its 20-year CfD extension, is designed to ‘reset confidence’ in offshore wind after two years of failed tenders and cost spikes. With that much activity moving through the market, the question of long-term asset stewardship is worth raising today, not later.

